

 Facebook
 X
 Pinterest
 Copy Link
Short answer: most Waldorf single-family detached homes are trading in the high
$300,000s to low $500,000s as of fall 2026, with attached homes and condominiums meaningfully below that — but the county median is the least useful number in that sentence.
Charles County’s median sale price was $435,000 in August 2026, down 3.3% from a year earlier, and Waldorf’s own all-housing-types median has been running near $420,000. That tells you the direction of the market. It does not tell you what your house is worth, because Waldorf is not one market. It’s three zip codes with meaningfully different price points, and inside them, a split between homes that sell quickly at close to full price and homes that sit and take a price cut.
That split is the real story here, and it’s why an online estimate can be off by tens of thousands of dollars in either direction.
Last updated: September 28, 2026.
A disclosure before I go further: I’m a listing broker, and I get paid when homes sell. Read what follows knowing that, and check the underlying data yourself — I’ve sourced all of it at the bottom.
Quick facts: the Waldorf and Charles County market right now
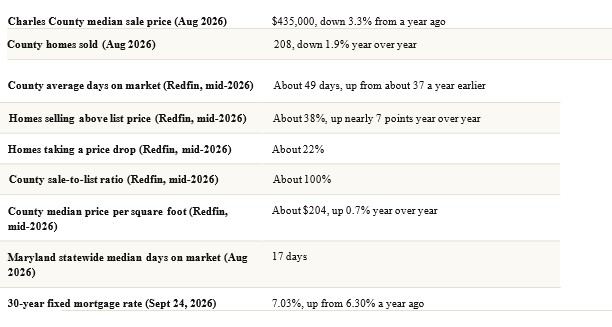
A word on days on market, because this is where most market commentary goes wrong. Redfin reports Charles County homes averaging about 49 days. Maryland REALTORS reports a statewide median of 17 days. Those are different measures from different datasets — an average and a median — and they are not directly
comparable. Averages on days-on-market run much higher than medians because a handful of listings that sit for a very long time pull the average up.
What both readings agree on is more useful than either number alone: the spread between fast listings and slow ones in this market is wide. Sale-to-list is sitting right around 100% and nearly four in ten Charles County
homes sold above asking, while roughly one in five took a price drop. Both are true at once, and the difference between them is almost entirely pricing and preparation.
How much is my Waldorf home worth in 2026?
Start with the honest range, then narrow it.
Waldorf’s three zip codes don’t trade at the same level. 20603 — the Western Waldorf / St. Charles corridor — generally runs highest, 20601 in the middle, and 20602 lowest. Published zip-level figures vary a lot by source and by whether they measure asking prices or closed sales, so I’d rather give you the ordering than a false-precision dollar figure. Ask me for the closed-sale medians in your specific zip and I’ll pull them.
Charles County’s closed median was $435,000 in August 2026. Price per square foot has been running near
$204 and is up slightly year over year, which is worth noting: the per-foot value of Charles County housing has held even as the median drifted down. That usually means the mix of what sold shifted toward smaller homes, not that every house lost value.
So a reasonable first pass for a typical Waldorf single-family detached home in average condition is the $400s, with the upper $400s and above reachable in 20603, in newer construction, and in updated homes. Attached
homes, condominiums, and a 20602 rambler needing work all land below that. None of which is your number. Here’s why.
Why is the Zillow estimate different from what my agent says my house is worth?
Because they’re answering different questions.
An automated valuation model — Zillow’s Zestimate, Redfin’s Estimate, and every “what’s my home worth” widget built on the same idea — is a statistical guess built from public records, tax assessments and recent
nearby sales. It’s genuinely useful for a rough bracket. It has no idea whether your kitchen was redone in 2024
or 1994, whether your basement is finished, whether your lot backs to woods or to Route 301, or whether the comparable sale down the street was a distressed transaction.
In a market like Waldorf’s, those gaps matter more than usual, for three specific reasons:
Subdivision mix. Waldorf contains everything from 1970s St. Charles-era townhomes to 2020s new construction. An AVM that averages across that range will pull an outlier toward the middle and miss.
Condition blindness. Because condition isn’t in the public record, an automated estimate can’t distinguish an updated house from a dated one on the same street. In practice that cuts both ways.
A softening median. When county prices are drifting down 2% to 3%, models that lean on older comps lag the market. When the market turns the other way, they lag going up.
A comparative market analysis works differently. It starts with what actually sold within roughly a half-mile of your address in the last 90 days, adjusts for square footage, condition, lot, and layout, then accounts for what’s currently competing with you. It’s built from the same closed-sales evidence an appraiser will review
independently, which is why it usually lands closer to an appraised value than an automated estimate does. A CMA is a broker’s opinion of value, not an appraisal.
Are home values going up or down in Waldorf?
Slightly down, and slowly.
Charles County’s median sale price fell 3.3% year over year in August 2026, and closed sales that month were down 1.9%, to 208. July was weaker on volume, down 14.7%. Meanwhile price per square foot has ticked up about 0.7%.
Read together, that’s a market where values are broadly holding but the top of the range has gotten harder to reach. It is not a decline in the sense most people fear. Sale-to-list is right around 100%, and homes that are priced correctly are still transacting at asking. I’m not currently seeing a surge of distressed listings in the Charles County inventory, though foreclosure activity is always worth watching.
What has changed is the cost of money. Freddie Mac’s 30-year fixed averaged 7.03% on September 24, 2026, up from 6.30% a year earlier, and the Federal Reserve raised its benchmark rate on September 16 for the first time in more than three years. Higher rates shrink what a given buyer can spend. Waldorf competes heavily on price with closer-in D.C. submarkets, and historically that kind of affordability pressure shows up first at the
upper end of each neighborhood’s range.
Forecasters aren’t promising relief soon. As of September 2026, the Mortgage Bankers Association projects 30-year rates near 6.8% through mid-2027, and Fannie Mae has it around 6.8% near-term easing to about 6.7%.
No major forecaster currently expects a return below 6%. Those are projections, not facts, and they get revised constantly — but the planning assumption should be rates in the high sixes to low sevens, not the threes.
How long are homes taking to sell in Waldorf?
Redfin puts the Charles County average at about 49 days, up from roughly 37 a year earlier. As noted above, that’s an average and it’s not comparable to the 17-day statewide median you’ll see quoted in Maryland REALTORS coverage.
What the trend supports is straightforward: market time in Charles County has gotten longer, not shorter. That’s the single best argument for taking your pricing seriously. Roughly one in five Charles County listings took a price drop, and most of those started with a seller who believed a number the market didn’t.
The flip side is genuinely encouraging: about 38% of homes sold above list price, up nearly 7 points from the year before. Well-prepared homes at defensible prices are still drawing competition. The market hasn’t gone soft on quality — it’s gone impatient with optimism.
What adds the most value to a Waldorf home?
In rough order of return in this specific market:
Condition and cleanliness before anything structural. Paint, flooring, decluttering, landscaping, and a deep clean. Many buyers financing at today’s rates are stretched on cash at closing, and in my experience they price in hassle on top of repair cost.
Kitchens and primary baths. Not gut renovations — surfaces, fixtures, lighting and hardware. Buyers read these two rooms as a proxy for how the whole house was maintained.
Finished lower levels. Waldorf’s stock is heavy on split-foyers and colonials with unfinished basements.
Finishing a basement with permits and a code-compliant egress window can add real marketability. Be aware, though, that appraisers report below-grade finished area separately from above-grade living area and generally give it less value per square foot. Confirm expected treatment with your agent or an appraiser before you
budget the project.
HVAC, roof and water heater documentation. Not an upgrade — a negotiation shield. Buyers discount unknown mechanical age, and in my experience they discount it by more than the fix would cost. Receipts and service records are cheap.
What doesn’t pay: pools, highly personalized finishes, and over-improving past your street. In a market where average market time is lengthening, the house priced well above everything around it is the house that sits.
How do I get an accurate value for my Waldorf home?
Three things, in order.
Pull your own comps first so you’re an informed participant — look at what actually closed within a half-mile in the last 90 days, not what’s listed. Listed prices are opinions; closed prices are facts.
Then get a comparative market analysis on your specific address from someone who works Charles County, not a regional average. A CMA is typically provided at no cost by a listing agent, and it’s a broker’s opinion of
value rather than an appraisal. Ask to see the comps and the adjustments, not just the conclusion. If an agent hands you a number without showing you the work, you’ve been given a marketing pitch.
Then, if you’re making a major decision on the number — a relocation, a divorce settlement, an estate — consider paying for a licensed appraisal. Residential appraisals in this market typically run several hundred dollars; ask for a quote up front. That’s cheap relative to mispricing a $450,000 asset.
Frequently asked questions
How much is my Waldorf, Maryland home worth in 2026?
Charles County’s median sale price was $435,000 in August 2026, down 3.3% year over year, and Waldorf’s all-housing-types median has been running near $420,000. Most Waldorf single-family detached homes are trading in the high $300,000s to low $500,000s, with attached homes and condominiums below that. Your specific
value depends on condition, square footage, lot and recent closed comps within a half-mile.
Are home prices going down in Waldorf, Maryland?
Slightly. Charles County’s median sale price is down 3.3% year over year (August 2026), and closed sales that month were down 1.9%. July was weaker on volume, down 14.7%. But price per square foot is up about 0.7% and sale-to-list is right around 100%. This is a flat-to-soft market, not a decline.
How accurate is the Zillow Zestimate for Waldorf homes?
It’s a reasonable starting bracket and an unreliable final number. Automated models can’t see condition,
renovations, layout or lot quality, and Waldorf’s mix of 1970s St. Charles housing and new construction makes those gaps larger than average. A comparative market analysis on your address will generally land closer to an appraised value.
How long does it take to sell a house in Waldorf?
Redfin puts the Charles County average at about 49 days, up from roughly 37 a year earlier. That’s an average, not directly comparable to the 17-day statewide median Maryland REALTORS reports. Correctly priced homes move faster; about 38% of county homes still sold above list price.
What is the most valuable Waldorf zip code?
20603 generally runs highest, followed by 20601, with 20602 lowest. Published zip-level dollar figures vary widely by source and by whether they measure asking prices or closed sales, so treat the ordering as reliable and any specific figure as needing verification against closed sales in your zip.
Should I get an appraisal or a CMA to find out what my home is worth?
A CMA is typically provided at no cost by a listing agent, is oriented toward what a buyer will actually pay, and is the right tool for a listing decision — but it is a broker’s opinion of value, not an appraisal. A licensed appraisal costs money and carries independent professional weight, which matters for estate settlements,
divorce, and tax or litigation matters.
SOURCES
- Maryland Association of REALTORS, August 2026 housing statistics (via The Washington Informer, 14, 2026)
- Redfin Charles County, MD housing market data, 2026
- Freddie Mac Primary Mortgage Market Survey, 24, 2026
- Federal Reserve FOMC decision, 16, 2026
- Fannie Mae and Mortgage Bankers Association rate forecasts, 2026–2027
This article is for general information and is not financial, tax, legal or appraisal advice. Market data changes; figures reflect the most recent available as of September 28, 2026. Redfin figures are averages and use Redfin’s own definitions; Maryland REALTORS figures are Bright MLS medians. The two are not directly comparable and are reported separately throughout.


