

 Facebook
 X
 Pinterest
 Copy Link
When does leasing make more sense?
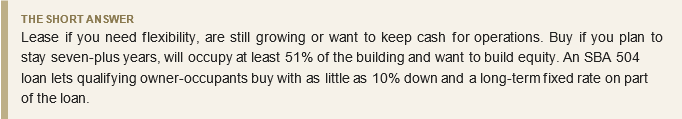
Leasing is usually the better fit when:
- Your business is young or your space needs may change in the next few
- You want to keep cash for hiring, inventory or
- You need a specific retail location – for example, a shopping center in Bowie, Columbia or Annapolis – where buildings rarely sell to small users.
- You prefer the landlord to handle roof, structure and major systems (depending on the lease type).
Watch the total cost, not just base rent. Many DMV retail, flex and industrial leases are triple net (NNN), meaning you also pay your share of real estate taxes, insurance and common area maintenance.
When does buying make more sense?
- You plan to stay in one location for many
- You want predictable occupancy costs and protection from rent
- You want to build equity, and possibly lease extra space to another
- Your business has two or more years of solid financials (and, for SBA, fits size standards).
How does an SBA 504 loan work?
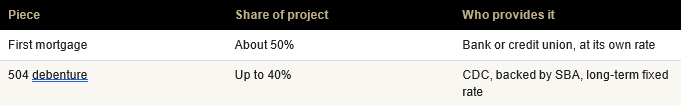
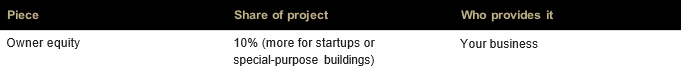
The SBA 504 program finances owner-occupied commercial real estate and long-life equipment through a Certified Development Company (CDC), such as those serving Maryland. A typical structure:
Key rules:
- Owner occupancy: for an existing building, your business generally must occupy at least 51% of the
- Terms: 10-, 20- and 25-year maturities are
- Loan size: SBA lists a maximum 504 debenture of up to $5.5 million for certain project types (commonly $5 million for standard projects); confirm with your CDC.
- Not eligible: working capital, inventory, or purely investment/rental real
- Startups and special-purpose properties often need 15% to 20%
The fixed rate on the CDC portion is set at a monthly SBA debenture sale and locked for the full term, which helps owners budget long-term.
How do the numbers compare?
Here is a simple illustration (not a quote) for a $1,000,000 owner-occupied flex building:
- Down payment at 10%: $100,000 plus closing costs
- Bank first mortgage: about $500,000
- 504 loan: about $400,000, plus SBA fees that are typically financed
Compare the monthly principal, interest, taxes and insurance to the full NNN lease cost of a similar space. Remember that part of each mortgage payment builds equity, while you also take on repairs and vacancy risk on any extra space.
What Maryland closing costs should buyers expect?
Commercial buyers in Maryland pay state and county recordation and transfer taxes, title insurance and lender fees. Rates vary by county – Prince George’s, Anne Arundel, Howard and Montgomery each set their own. Ask your title company for a jurisdiction-specific estimate early.
Where can Maryland business owners get help?
- Maryland Small Business Development Center (SBDC): free advising on financing and business
- Maryland Department of Commerce and the Maryland Small Business Development Financing Authority (MSBDFA) for state financing programs.
- County economic development offices, such as the Prince George’s County Economic Development Corporation, Anne Arundel Economic Development Corporation and Howard County Economic Development
Before deciding, check zoning for your use and, in Prince George’s County, the Use and Occupancy permit requirement – it applies whether you lease or buy.
What questions should I ask before deciding?
- How many years do I expect to stay, and how much space will I need in five years?
- What is my all-in monthly cost to lease (base rent plus NNN charges and annual increases)?
- What is my all-in monthly cost to own (both loans, taxes, insurance, maintenance reserves)?
- Do I have the down payment and still enough working capital to run the business?
- Does the zone allow my use, and will I need a building permit or change of occupancy?
- Could I lease part of the building to another tenant to offset costs?
Your accountant can also explain the tax differences between deducting rent and owning (interest, depreciation), which often influence the decision. Finally, have a commercial agent pull recent lease and sale comparables for your submarket so you are comparing real options, not estimates.
Frequently asked questions
What is the minimum down payment on an SBA 504 loan?
Typically 10% of the project cost. Startups and special-purpose properties often need 15% to 20%.
Can I buy a building with an SBA 504 loan and rent part of it out?
Yes, as long as your business occupies at least 51% of an existing building. Purely investment property is not eligible.
Is it cheaper to buy or lease commercial space?
It depends on how long you will stay, rates and the property. Buying often costs more up front but builds equity; leasing preserves cash and flexibility. Compare full NNN lease costs to total ownership costs.
What is a NNN lease?
A triple net lease means the tenant pays base rent plus its share of property taxes, insurance and common area maintenance.
How long does an SBA 504 loan take?
Timelines vary, but plan for several weeks to a few months for lender and CDC approval, appraisal and environmental review.

Sources
- S. Small Business Administration – 504 Loans: https://www.sba.gov/funding-programs/loans/504-loans
- Lev – SBA 504 Loans for Owner-Occupied CRE in 2026: https://www.lev.com/blog/sba-504-loans-owner-occupied-cre-2026
- TMC Financing – SBA 504 Loan Limits: https://www.tmcfinancing.com/sba-504-loan-limits-how-much-can-i-expect-to-get/
- Maryland Small Business Development Center: https://www.marylandsbdc.org/
- Maryland Department of Commerce – Financing Programs: https://commerce.maryland.gov/fund
Program terms, rates and limits change. Information current as of October 29, 2026; confirm details with the agency or your lender. This article is general information, not legal, tax or lending advice.
About the author: Reggie Butler
Broker/Owner, CENTURY 21 ENVISION
Reggie Butler leads CENTURY 21 ENVISION in Bowie, Maryland, helping buyers, sellers, investors and business owners across Washington DC, Maryland and Northern Virginia with residential sales and commercial leasing and acquisitions.
1318 Crain Hwy, Bowie, MD 20716 · 240-232-7005 · 240-938-1244
reggiebutler333@gmail.com · www.c21envision.net
Each office is independently owned and operated. Equal Housing Opportunity.


